
By AtheneNet Money Desk | 15 August 2026
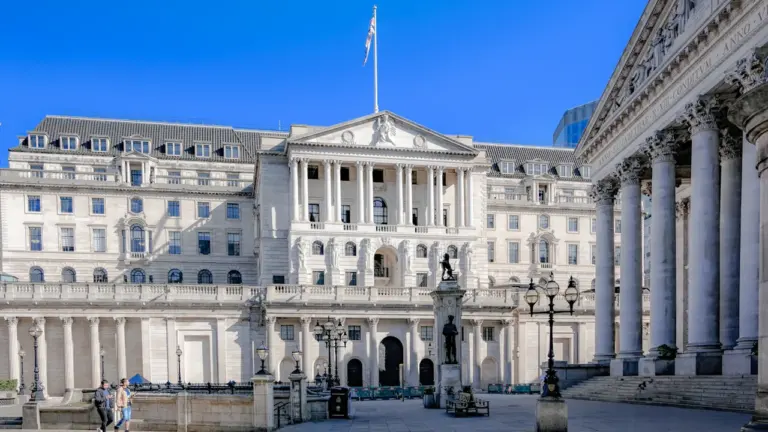
The Bank of England has scheduled its next Monetary Policy Report and interest-rate announcement for 17 September 2026. The decision could affect households with variable-rate mortgages, people preparing to remortgage and savers seeking competitive returns, but the published calendar alone provides no basis for assuming that Bank Rate will fall.
At a glance
- Question: Will the MPC lower Bank Rate at its September meeting?
- Deadline: The scheduled announcement is 17 September 2026.
- YES: The announced rate is below the rate in force immediately beforehand.
- NO: Bank Rate is unchanged or increased.
- The Bank of England’s published announcement and rate history will settle the result.
Why the September decision remains genuinely open
The Bank of England’s MPC calendar establishes the decision date. Its separate Bank Rate page identifies Bank Rate as the interest rate set by the Monetary Policy Committee and publishes the current rate and its official change history.
Those facts create a clear deadline and baseline, but they do not predict the vote. The rate in force immediately before the announcement is particularly important because that is the figure against which any September change must be measured.
A cut becomes more plausible when inflation is moving sustainably towards the Bank’s target, domestic price pressure is easing and economic activity appears weak enough to justify less restrictive policy. The case for holding strengthens when services inflation or wage growth remains persistent, even if headline inflation has improved.
An increase would normally require evidence that inflation pressure is rebuilding or becoming harder to contain. It belongs within the NO outcome for this forecast, although its effects on households would differ sharply from those of an unchanged rate.
The responsible position on 15 August is therefore conditional rather than certain. The September decision remains forecastable because it has a public deadline and an objective result, but the official calendar should never be mistaken for a signal about how the committee will vote.
Inflation and pay data will shape the MPC vote
Consumer price inflation and wage growth are likely to be central to the September discussion. Headline inflation shows the overall change in consumer prices, while services inflation can offer a clearer view of domestically generated pressure. Wage indicators matter because sustained pay growth can support demand and feed through to service-sector costs.
The Bank pages establishing the decision date and Bank Rate history do not themselves provide a current inflation or earnings reading. The latest releases from the Office for National Statistics available before the meeting will therefore be essential. Without those figures, assigning a strong directional advantage to either outcome would create false precision.
The trend matters more than one release
A single softer inflation figure would not automatically produce a cut. MPC members can examine whether the change is broad, whether volatile components caused it and whether underlying measures point in the same direction.
The same caution applies to earnings. A weakening labour market could reduce future wage pressure, but high measured pay growth may still concern policymakers. Revisions and differences between private-sector, public-sector and bonus-adjusted measures can also alter the interpretation.
Policymaker comments require similar discipline. A statement by one MPC member is an attributed view, not a committee commitment. Dated speeches, hearing testimony, meeting minutes and the recorded vote split can clarify individual positions, but the September outcome will be determined collectively at the meeting.
The clearest pro-cut signal would be several members consistently describing inflation pressure as sufficiently contained to reduce restraint. Repeated warnings about persistent services prices, wages or inflation expectations would strengthen the hold case. Neither type of language should be treated as a guarantee.
A cut would reach mortgages unevenly
A September reduction would not lower every mortgage payment immediately. Tracker mortgages normally move in line with Bank Rate under their contractual terms, so affected borrowers could see the most direct transmission after a cut.
Standard variable rates are set by individual lenders. They often respond to Bank Rate changes, but lenders decide the size and timing of any adjustment. Borrowers should check their lender’s notice rather than assume that the full MPC change will be passed on.

Existing fixed-rate mortgages would ordinarily continue at their agreed rate until the fixed period ends. For those households, the important question is what happens to remortgage offers. Fixed mortgage pricing reflects wholesale interest-rate expectations, lender funding costs, competition and borrower risk as well as the current Bank Rate.
That means fixed deals can become cheaper before an MPC cut if financial markets already expect one. They can also remain expensive after a cut if longer-term funding costs rise. Waiting solely for 17 September could therefore be costly for someone whose fixed term is about to expire.
Borrowers approaching renewal can compare available offers, note how long each offer remains valid and consider whether a product permits switching to a cheaper deal before completion. Arrangement fees, early-repayment charges and the reversion rate matter alongside the advertised interest rate.
Savers, consumer borrowers and sterling face different effects
Savers could experience the other side of a rate cut. Easy-access providers may reduce returns relatively quickly, although competition for deposits can delay or soften the change. A fixed-term account generally preserves its agreed rate until maturity, subject to its terms.
Someone who needs ready access to cash should not choose a long fix based only on the September forecast. Withdrawal restrictions, deposit protection eligibility and the timing of future expenses remain important. Comparing the annual equivalent rate and account conditions is more useful than reacting to a single policy headline.
Credit cards, overdrafts and personal loans do not track Bank Rate mechanically. Lenders also price for credit risk, operating costs and competition, so a modest MPC cut may produce little or no immediate reduction in an existing borrower’s rate.
Sterling could weaken if a cut is more accommodative than investors expected, making imports more expensive in pound terms. However, currency moves are relative: expectations for other central banks, economic growth, fiscal developments and global risk sentiment can outweigh the UK decision. A widely anticipated cut may already be reflected in exchange rates before the announcement.
The hold-or-rise case matters to household planning
A hold would leave Bank Rate unchanged on decision day, but it would not freeze every retail rate. Mortgage and savings providers can still reprice products as funding costs and expectations change. The MPC’s vote split and accompanying projections may influence those moves even when the headline rate stays put.
An increase would place more immediate pressure on tracker borrowers and could support some savings rates, although pass-through would remain uneven. It could also strengthen sterling if the move surprised markets, but there is no automatic currency response.
For households, the practical lesson is to plan around affordability rather than one forecast. Mortgage applicants can test payments at a higher rate, while savers can separate emergency cash from money suitable for a fixed term. Consumer borrowers should compare total repayment costs rather than assume that a possible cut will quickly make unsecured credit cheaper.
How the September forecast will be settled
The result will use the Bank of England’s published Bank Rate announcement and official rate history. It resolves YES only if the rate announced on 17 September 2026 is lower than the rate in force immediately before that announcement. It resolves NO if the rate is unchanged or increased.
An earlier change in Bank Rate would alter the comparison baseline but would not, by itself, settle this question. The relevant comparison is always the rate immediately before the scheduled September announcement against the rate announced at that decision.
If the decision is postponed, the forecast will remain pending until the replacement decision. The declared long-stop is 31 December 2026 at 23:59 London time. If no replacement decision has occurred by then, the forecast will close as unresolved rather than forcing an unsupported YES or NO result.
The next useful checks are the inflation and earnings releases available before the meeting, the latest MPC minutes and vote split, and any dated public remarks by named committee members. The decisive evidence will arrive on the Bank of England’s announcement page on 17 September.
Source: Bank of England
Context & actions About this article
Source check Forecast basis
The outcome will be determined from the Bank of England’s published rate announcement and official Bank Rate history.
- Confirm the Bank Rate in force immediately before the decision.
- Compare it with the rate announced on 17 September 2026.
- Treat an unchanged or higher rate as NO.
- Keep the forecast pending if the scheduled decision is postponed.
- Source
- Bank of England MPC dates
- Scope
- United Kingdom
- Updated
- 2026-08-15 14:39
Source check
Report a trust issue
Send a clear signal to community moderation if the source, facts or context need review.

Comments