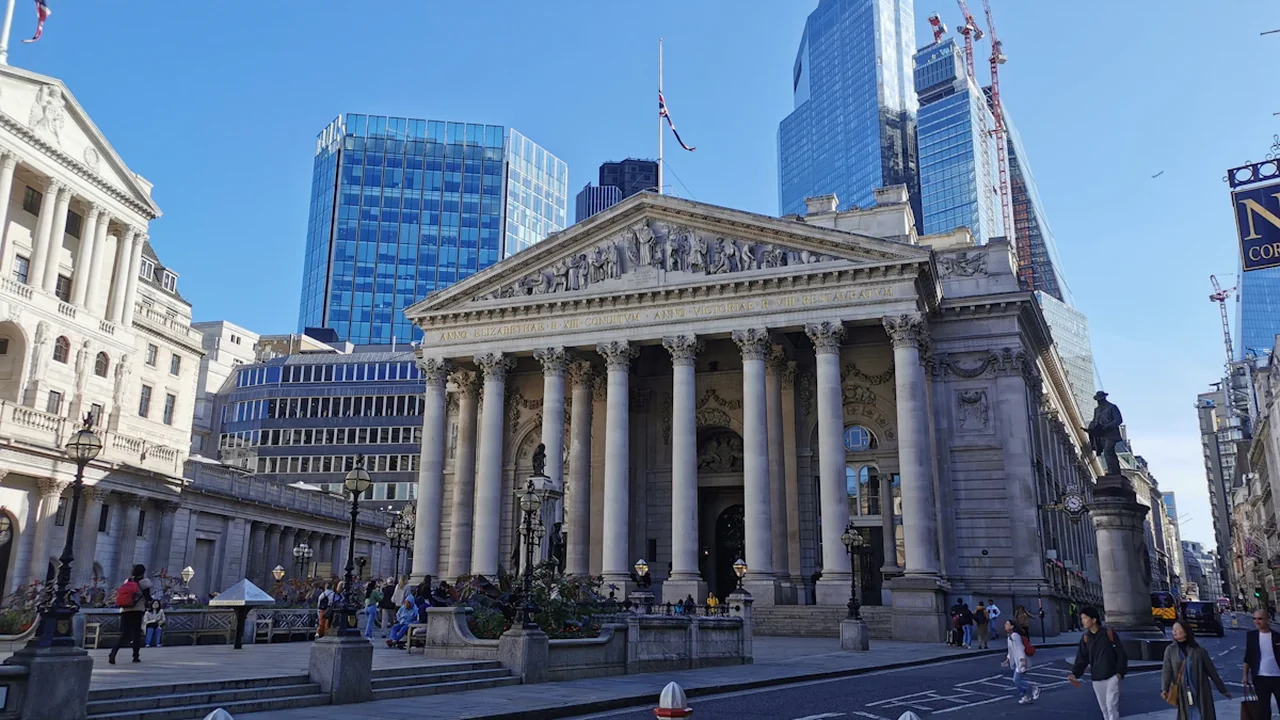
The Bank of England’s Monetary Policy Committee is scheduled to announce its next Bank Rate decision on 5 November 2026, a date that could influence the direction of some UK mortgage and savings products. The Bank Rate is the central bank’s official interest rate, and the committee responsible for monetary policy will publish its decision on that scheduled announcement date. For this forecast, the deadline matters because the outcome is determined solely by whether the announced rate is the same as it was immediately before the decision.
Decision snapshot
- Will Bank Rate remain unchanged on 5 November 2026?
- Deadline: 5 November 2026, when the MPC decision is announced.
- YES: The newly announced Bank Rate matches the rate immediately before the decision.
- NO: The MPC announces either a rate rise or a rate cut.
- Deciding record: The Bank of England’s official monetary policy announcement.
Why the 5 November Bank Rate decision matters to households
Bank Rate is an important benchmark for borrowing and saving across the UK, but its effects are neither instant nor identical for every household. A decision to hold, raise or cut the rate can shape lenders’ and savings providers’ pricing decisions, yet providers set their own products and terms.
For people remortgaging, choosing a savings account or managing a tracker mortgage, the November decision may provide a fresh signal about the interest-rate environment. It is not, however, a guaranteed instruction that every mortgage payment or savings return will change on the same day.
The Monetary Policy Committee, commonly called the MPC, is the Bank of England body responsible for setting monetary policy, including decisions on Bank Rate. Its scheduled announcement is therefore the public event that settles this specific question.
A hold would mean the MPC judged that the existing Bank Rate should remain in place at that meeting. It would not necessarily mean that inflation, household costs or lender pricing have stopped moving. A rate rise or reduction would show that the committee chose a different level for Bank Rate, while individual providers would still decide how and when to alter their own rates.
The result hinges on one simple comparison
This forecast does not ask whether Bank Rate is high, low, helpful or harmful. It asks a narrower question: is the rate announced on 5 November exactly unchanged from the rate in force immediately before that announcement?
The YES outcome
YES applies if the MPC leaves Bank Rate at the existing level. The official announcement may include economic analysis, voting details and commentary about inflation or growth, but those details do not alter the result if the headline Bank Rate is unchanged.
For example, if Bank Rate is at one level before the meeting and the MPC announces the same level on 5 November, the result is YES. A unanimous vote is not required for this outcome. Members can disagree about policy while the final published rate remains unchanged.
The NO outcome
NO applies if the MPC changes Bank Rate in either direction. A rise of any size is a NO result, and a cut of any size is also a NO result.
The scale of the move does not affect the result. A small adjustment and a larger adjustment both count as a change because the announced Bank Rate would no longer match the rate immediately before the meeting.
A Bank Rate hold does not freeze every mortgage rate
The most immediate household question is often whether a Bank Rate decision will change a monthly mortgage payment. The answer depends on the mortgage type, the lender’s terms and the timing of any provider announcement.
Tracker mortgages are commonly designed to move in relation to Bank Rate or another stated benchmark. If a tracker is explicitly linked to Bank Rate, a change by the MPC may affect the interest charged under the deal, subject to the mortgage contract. A hold is more likely to mean no Bank Rate-linked change to that element of pricing, though borrowers should still read their own terms.
Standard variable rate mortgages are different. A lender can decide whether and when to change its standard variable rate. Bank Rate may influence that decision, but it does not automatically dictate it. A provider may pass through all, some or none of a Bank Rate change, and its notice period may vary.
Fixed-rate mortgages work differently again. The interest rate is normally fixed for the agreed introductory period, so a Bank Rate decision will not usually alter the borrower’s rate during that fixed term. It can still matter for people nearing the end of a deal, comparing remortgage offers or considering a new fixed-rate product, because lenders may review future product pricing as market expectations change.
A household with a fixed deal ending soon should focus on the rate and expiry date in its own mortgage offer rather than assuming a November hold will preserve every available remortgage quote. Product withdrawals, replacement deals and affordability checks can all affect the options available.
Savings accounts can respond differently from mortgages
Savings providers also make their own pricing decisions. An easy-access or variable-rate savings account may change after a Bank Rate decision, but there is no universal rule that every account must move by the same amount or on the same date.
Some accounts include rates that are fixed for a set period. Those products generally retain their stated return until the term ends, unless their conditions say otherwise. Other accounts may include introductory bonuses, balance limits or withdrawal restrictions that matter as much as the headline annual interest rate.
A hold on 5 November could mean a provider leaves a variable savings rate unchanged, but it could also review rates for competitive reasons unrelated to a same-day policy move. Similarly, a Bank Rate rise would not guarantee that every saver receives a matching increase.
Before switching accounts, compare the underlying rate, any temporary bonus, access rules, minimum or maximum balance conditions and the provider’s notification arrangements. Savers should not make decisions solely from a Bank Rate headline.
What remains uncertain before the MPC announcement
The Bank of England has confirmed the institutional framework: Bank Rate is its official interest rate and the MPC makes the decisions. It has also scheduled the monetary policy announcement for 5 November 2026. Those are known facts.
What is not known in advance is the committee’s final decision. The MPC will assess the information available at the time, including its view of inflation and the wider economy. Public debate, forecasts and market expectations may offer context, but none of them settles the result before the official announcement.
Readers should also separate an expectation of a hold from a confirmed hold. A forecast can be reasonable while still being wrong, particularly when new economic information arrives before a decision date.
The clearest practical approach is to avoid treating the forecast as personal financial advice. Mortgage borrowers should check their product terms, payment-change notices and lender communications. Savers should check their provider’s rate page and the conditions attached to their account.
How to check the result and act after the decision
On 5 November, the decisive item will be the Bank of England’s published MPC decision. Check the announced Bank Rate against the rate immediately before the meeting:
- If the two rates are identical, the forecast resolves YES.
- If the announced rate is higher, the forecast resolves NO.
- If the announced rate is lower, the forecast resolves NO.
Afterward, give lenders and savings providers time to publish any product-specific changes. A Bank Rate decision is an important signal, but the relevant number for a household budget is the rate in that household’s own mortgage or savings account.
For borrowers, check whether the mortgage is fixed, tracker or variable and look for any message from the lender about payment dates. For savers, check the account’s current rate, bonus expiry and withdrawal rules. The next meaningful check is the Bank of England’s official 5 November decision, followed by the pricing notice from the provider that holds your account.
Source: Bank of England
Context & actions About this article
Source check Decision check
The outcome is determined by the Bank of England’s published Bank Rate decision on the scheduled date.
- Compare the announced Bank Rate with the rate immediately before the meeting.
- Use the Bank of England’s monetary policy announcement as the deciding record.
- Check your lender or savings provider for account-specific rate changes.
- Source
- Bank of England: Bank Rate
- Scope
- United Kingdom
- Updated
- 2026-09-13 10:16
Source check
Report a trust issue
Send a clear signal to community moderation if the source, facts or context need review.



Comments